

9th October 2025 | Data updated 02.11.26
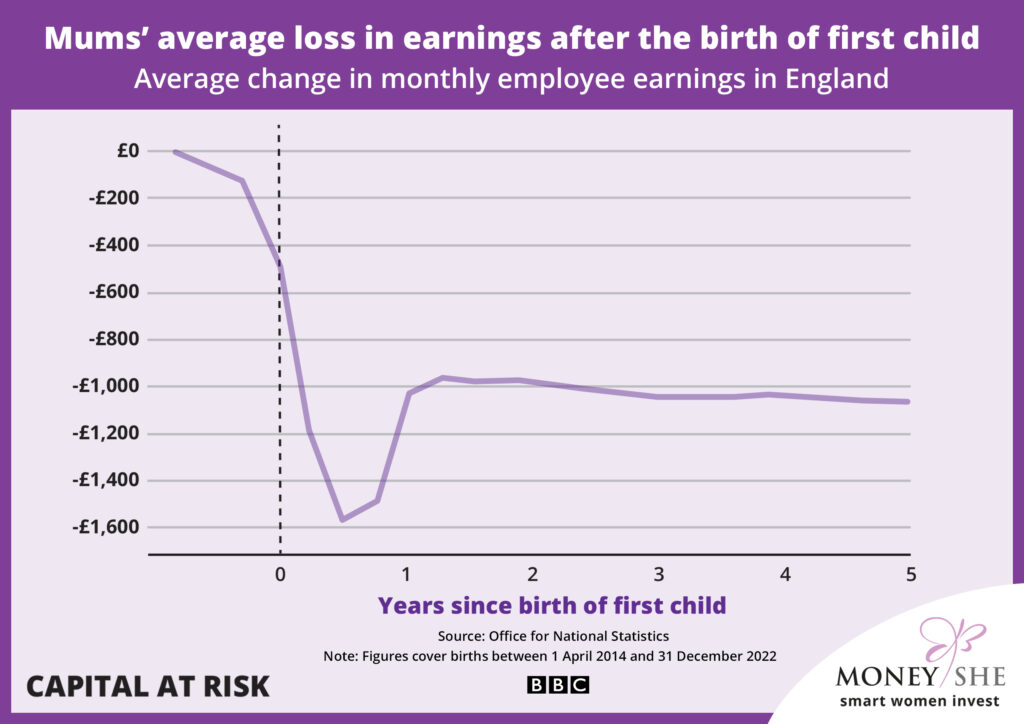
Having a child should be one of life’s most joyful milestones, not a trigger for financial loss. Yet in England today, five years after having a first child, a mother’s monthly earnings are on average 42% lower than in the year before she gave birth.
According to the most recent research by the Office for National Statistics (ONS), published in October 2025, mothers in England lose an average of £65,618 in cumulative pay by the time their first child turns five.
And this is not a short-term blip – it leads to a long-term financial hit with compounding consequences.
The Real Cost of Motherhood in the UK
Let’s look at the key data contributing to this outcome:
- 42% lower monthly earnings (around £1,051 a month) five years after a first child, compared with the year before birth
- £65,618 average earnings loss in the five years after a first child
- A further £26,317 lost in the five years after a second child
- A further £32,456 lost after a third
- Up to 15 percentage points fall in the likelihood of being in paid employment after a first child
Source: ONS, covering England from April 2014 to December 2022, in 2023 prices. These remain the latest ONS estimates.
The majority of these losses stem from reduced working hours, missed promotions, career stagnation, and lower pay upon re-entry to the workforce.
“This is not just a personal cost. The UK economy loses too through loss of talent, productivity, and potential when women are financially penalised for motherhood.”
Case Study: Anna’s Five-Year Financial Setback
Anna, 33, was earning £36,000 annually in a mid-level marketing role before her first child. She returned to work part-time, missing out on a promotion and annual bonuses. Her new monthly income dropped to £1,740 – about 58% of her previous salary.
Five years later, her cumulative shortfall = £75,600, not including lost pension contributions or slowed salary progression. Even as she increases hours later, she faces an uphill climb against peers who never paused for parenthood.
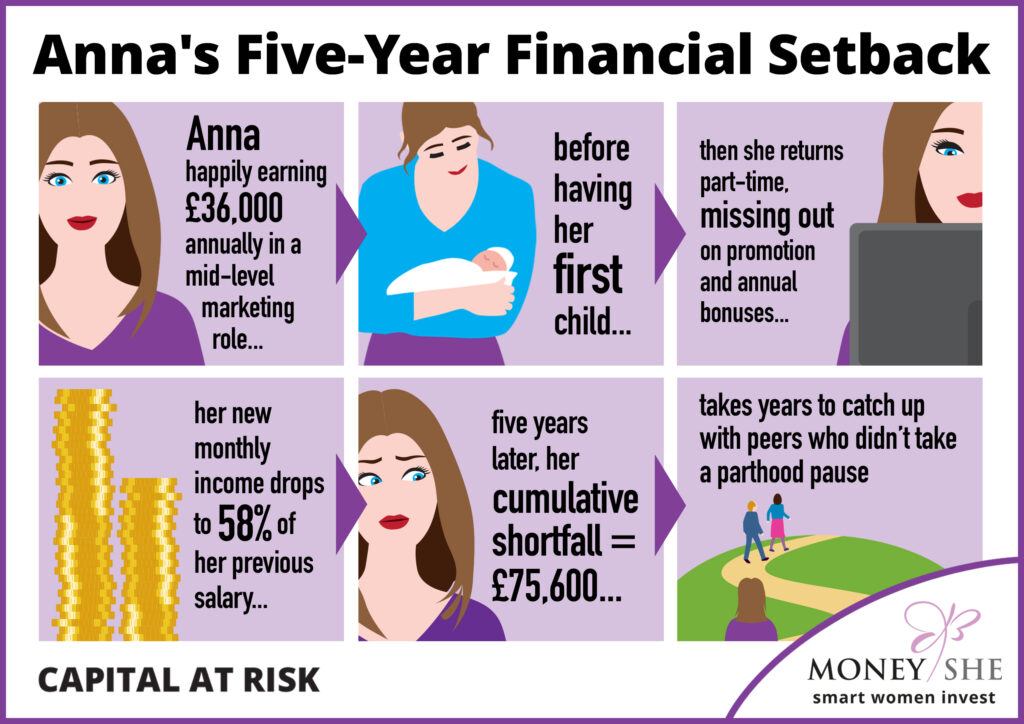
Anna’s story is not unique; it mirrors what is happening across the UK.
Why the Penalty Exists
The motherhood penalty is driven by several systemic factors:
- Career interruptions due to maternity leave and caregiving
- Shift to part-time or lower-paid roles for flexibility
- Missed promotions and reduced visibility at work
- Employer bias, often subconscious, about a mother’s “commitment”
- Cumulative compounding, where smaller salaries mean smaller raises, bonuses, and pensions
Together, these effects create consequences that can last decades.
The Bigger Picture: A National Issue
Beyond personal finance, the motherhood penalty has wide-reaching impacts:
- Gender Pay Gap: Parenthood is a key driver of a gap that still stood at 12.3% across all UK employees in April 2026 (ONS). Among full-time employees, it doubles from 4.1% for those in their 30s to 8.2% for those in their 40s.
- Retirement Inequality: Reduced pensions from lower lifetime earnings
- Unequal Impact: Single mothers and women from minority backgrounds are hit harder
The Hidden Economic Cost of Poor Childcare: Why the UK Can’t Afford to Lose Working Mothers
Let’s dig deeper into the wider economic cost and why this issue is not just one for women but everyone.
As thousands of women across the UK step back from their careers due to unaffordable or inaccessible childcare, the country faces a quieter but mounting financial crisis.
Whilst the ONS study revealed that mothers in England lose an average of £65,618 in earnings in the first five years after having their first child, behind that number lies a much larger issue. The fact that we as a country are systematically underutilising the talent and productivity of half the population. The result? A drag on national growth, household income, and long-term economic health.
Why Women Leave the Workforce
The core issue is clear – childcare in the UK is among the most expensive in the OECD. According to the OECD’s most recent comparison (2022 data), net childcare costs for a UK couple with two young children come to around 19% of average wages – nearly double the OECD average of 10% – making the UK the fourth most expensive country in the OECD for childcare.
Faced with costs that often rival a second mortgage, many women are making a financially rational, but a nationally damaging decision to scale back or quit work entirely.
While men also face family pressures, it is overwhelmingly women who absorb the childcare burden. Whether due to wage gaps, social expectations, or inflexible working norms, women are more likely to adjust their careers around family life.
This dynamic isn’t just unfair – it’s inefficient.
The Economic Fallout
When women reduce or leave their participation in the workforce, the effects extend far beyond their own earnings, and the broader economy feels the impact:
- Lower Labour Force Participation: A smaller working population means slower economic growth. If more mothers remained in work, the UK’s GDP could rise substantially. In fact, if female employment matched male levels, the UK economy could gain tens of billions in annual output.
- Reduced Tax Revenue: With fewer women earning wages, the government collects less income tax and National Insurance. That’s revenue that could have funded better public services – ironically, including childcare.
- Greater Pressure on Public Services: Families that struggle financially due to lost income may need more support from state benefits, housing subsidies, or child allowances—costing the public purse even more.
- Skills Wasted: Talented, educated women dropping out of the workforce represents a vast waste of human capital. Years of education, training, and professional experience are left untapped— impacting innovation, leadership, and sectoral growth.
Suggested Fixes
Fortunately, there are ways to reverse this trend, and countries that have done so are reaping the benefits.
- Affordable Childcare Provision: Government-subsidised, high-quality childcare has been shown to boost maternal employment. For every £1 invested, returns in GDP growth, tax revenue, and reduced benefit reliance often exceed the outlay. In England, funded childcare for eligible working parents expanded to 30 hours a week from September 2025, starting from the term after a child turns nine months. That is real progress, but the hours usually apply only in term time (38 weeks a year), so many parents still pay for holidays and any hours beyond the funded entitlement.
- Workplace Flexibility: Employers who offer remote work, job sharing, and flexible hours not only retain more women—they boost productivity, morale, and retention.
- Shared Parental Leave and Culture Shift: Policy must support—not penalise—families who want to share caregiving responsibilities more equally.
- Support for Re-entry: Career breaks for caregiving shouldn’t mean permanent penalty. Upskilling, mentoring, and return-ship programs can ease the path back to work.
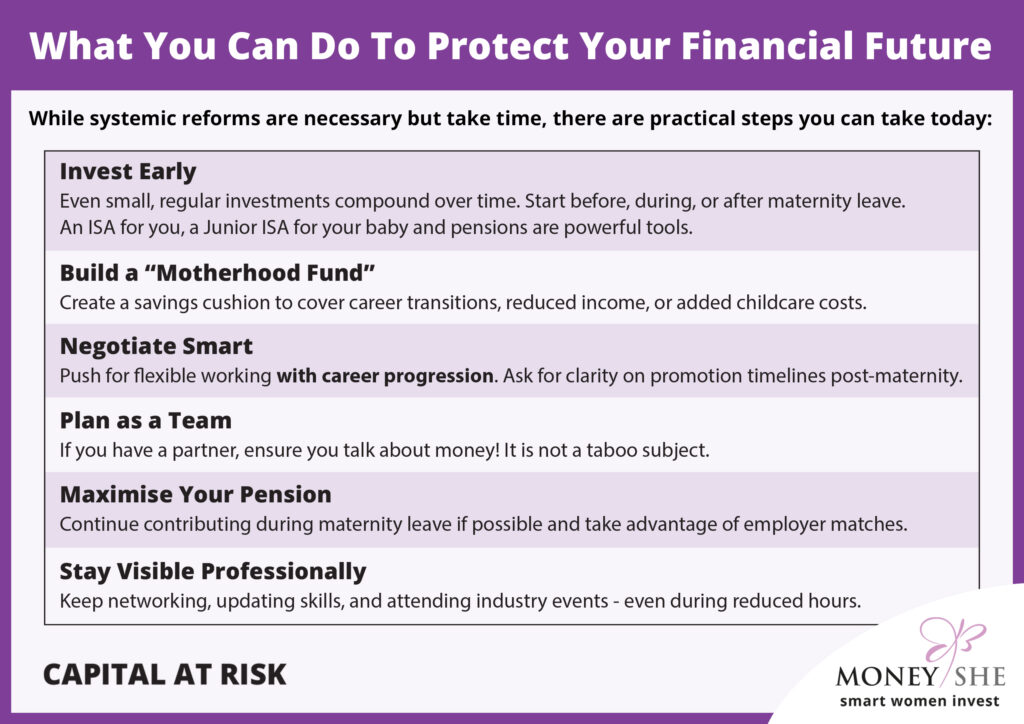
What You Can Do To Protect Your Financial Future
While systemic reforms are necessary but take time, there are practical steps you can take today:
How MoneyShe Can Help
At MoneyShe, we empower women to reclaim their financial power- especially during life transitions like motherhood.
Here’s what we offer:
✅ Easy-to-understand investment guides
✅ Access to low cost, risk-adjusted, highly diversified portfolios
✅ Quarterly Webinars
✅ Smart Tools for risk analysis and costs
We believe motherhood should never mean financial vulnerability. You deserve support, resources, and access to financial products that will look after your future financial health and wealth.
Final Word
The 42% earnings loss mothers face isn’t just a personal setback – it’s a national challenge we all need to address.
But until policy and workplace reform catch up, women must act in their own interest and equip themselves and their family for a healthy financial future that affords a comfortable lifestyle, security and choices.
Start now. Invest in yourself. Build the financial resilience to thrive, on your terms.
🟣 Join the MoneyShe community today and take the first step toward reclaiming your financial future.
👉 Explore our tools and start investing now
Important Notice:
This is general information only and not financial advice. The value of investments can go down as well as up, so you could get back less than you invest. It is therefore important that you understand the past performance is not a guide to future returns. None of the trading brands of SCM Private, MoneyShe or SCM Direct – give personal advice based on your circumstances. We aim to provide investors with understandable information so they can make fully informed decisions. If you are unsure about the suitability of our investment portfolios, please contact an independent financial adviser.